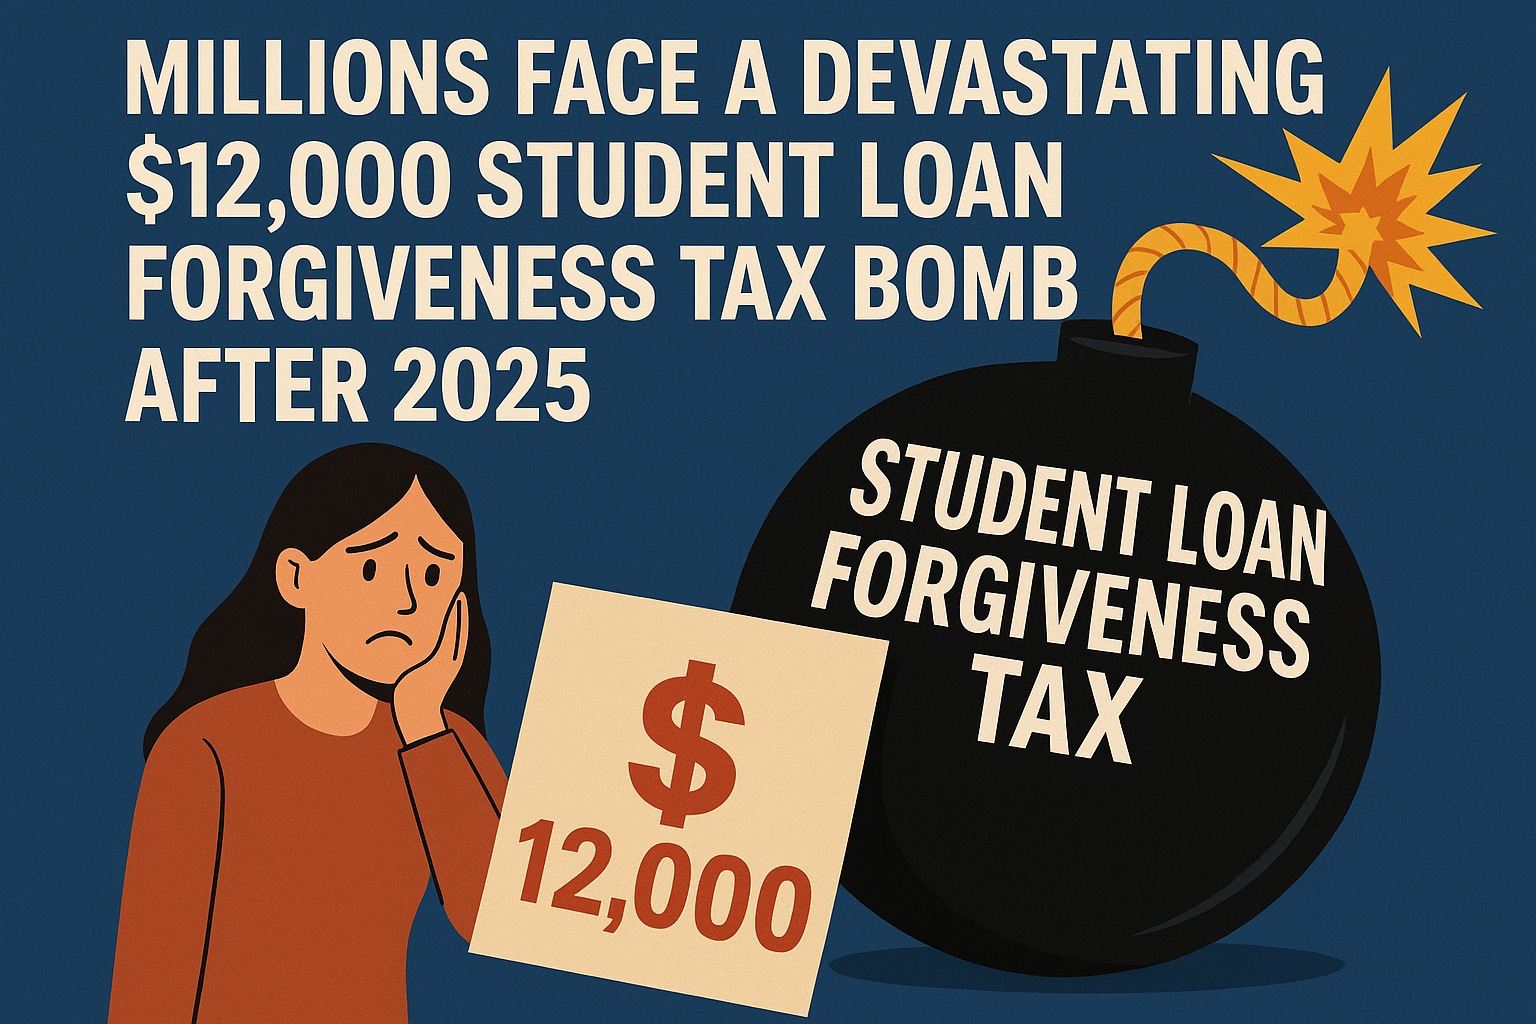

Imagine finally reaching the finish line, years of diligent payments behind you, only to find a new, unexpected bill waiting. That’s the chilling reality facing millions of federal student loan borrowers, according to a stark warning from the advocacy group Protect Borrowers. They’re ringing the alarm about a looming “student loan forgiveness tax bomb” that could hit up to 3 million Americans with an average tax bill of nearly $12,000 on their supposedly forgiven debt. It’s a twist that feels both cruel and, for many, entirely unforeseen, turning a moment of anticipated relief into a fresh financial nightmare.
This isn’t some abstract theoretical problem. We’re talking about real people, often those with modest incomes, who have faithfully navigated the complexities of income-driven repayment (IDR) plans for decades. They’ve made their payments, sometimes just pennies, for 20 or 25 years, believing that at the end of that arduous journey, their remaining balance would simply vanish. And for a while, thanks to temporary federal relief, it largely did so without immediate tax implications. But that crucial tax exemption is set to expire at the close of 2025, leaving a gaping hole that could swallow the financial stability of millions.
Protect Borrowers didn’t just speculate; their recent report, released this week, lays out a grim projection. For many low-income Americans, particularly those earning under $60,000 annually and with little to no savings, this isn’t just an inconvenience. It could mean their annual tax bill doubles or even triples, effectively swapping one debt — their student loan — for another, equally formidable one with the IRS. It’s a development that’s rightfully generating massive social media engagement, sparking outrage and concern, because it’s not just a policy oversight; it’s a potential financial catastrophe for families who thought they were finally free.
The Looming Threat: What Exactly is the Student Loan Forgiveness Tax Bomb?
To understand the depth of this problem, let’s break down what a “student loan forgiveness tax bomb” actually means. Typically, when a debt is forgiven, the IRS treats that forgiven amount as taxable income. Think of it this way: if a bank forgives $10,000 you owed them, the government views that $10,000 as if you earned it, and thus, it’s subject to income tax. For many years, this was the standard for most student loan forgiveness programs, including those under income-driven repayment plans.
However, a critical change came with the American Rescue Plan Act of 2021. This legislation included a provision that temporarily exempted certain student loan forgiveness from federal income tax. This was a massive relief for borrowers, especially those whose loans were being discharged through IDR plans, which often leave substantial balances after two or two-and-a-half decades of payments. This exemption was a lifeline, ensuring that borrowers who finally achieved forgiveness wouldn’t be immediately crushed by a hefty tax bill. But here’s the kicker: this federal tax exemption isn’t permanent. It’s set to expire on December 31, 2025.
When that exemption vanishes, any federal student loan debt forgiven after that date – specifically, balances discharged through income-driven repayment plans – will once again be treated as taxable income by the IRS. So, if you have $50,000 in student loan debt forgiven in January 2026, and you’re in a 22% tax bracket, you could suddenly owe $11,000 in federal income tax. That’s a significant chunk of change, especially for someone who just spent 20+ years struggling to pay down their loans, often making minimal payments because their income was too low to cover the full principal and interest.
The report from Protect Borrowers highlights that it’s precisely these long-term IDR plan participants who are most at risk. These aren’t people who defaulted yesterday; these are individuals who have been faithfully, if minimally, paying for two decades or more. Their remaining balances are often substantial because their initial incomes were low, or they experienced periods of unemployment or underemployment, meaning their payments didn’t keep pace with interest accrual. The irony is bitter: after decades of struggling to manage their debt, they could face a new, equally daunting financial challenge from the very system designed to offer them relief. (See: U.S. Department of Education Overview.)
Who’s Most Vulnerable to This IDR Forgiveness Tax Hit?
The Protect Borrowers report makes it abundantly clear: this isn’t a problem that will affect everyone equally. The “student loan forgiveness tax bomb” will disproportionately detonate in the financial lives of America’s most economically vulnerable. Think about it: who uses income-driven repayment plans for 20 or 25 years? It’s generally not the high earners who can pay off their loans quickly. It’s individuals whose incomes have been consistently modest relative to their debt, or who’ve experienced career setbacks, health issues, or other life events that have kept their earnings low.
The report projects that many of the 3 million borrowers at risk earn under $60,000 annually. For someone in that income bracket, an unexpected tax bill of nearly $12,000 isn’t just a nuisance; it’s potentially devastating. It could be the equivalent of several months’ rent, a major car repair, or a significant portion of their annual income. Many of these borrowers have minimal savings, if any. They’re living paycheck to paycheck, and the idea of absorbing such a large, unanticipated tax liability is simply unfathomable.
Consider a single parent working multiple jobs, making just enough to get by. They’ve been on an IDR plan for years, chipping away at their loans. Finally, their remaining balance is forgiven. But then, they receive a tax form (a 1099-C) reporting that forgiven amount as income. Suddenly, that single parent, who might normally get a small tax refund, could owe thousands. This new debt to the IRS isn’t just an abstract number; it’s food on the table, childcare expenses, or the ability to keep the lights on. It fundamentally undermines the very purpose of IDR plans, which were designed to provide a safety net for borrowers struggling to afford their payments.
Furthermore, the problem isn’t confined to federal loans directly. While the federal tax exemption expiring is the primary driver, borrowers in states that do not conform to federal tax law regarding forgiven debt could face state income tax liabilities as well, compounding the problem. While some states have taken steps to align their tax codes with federal exemptions, it’s not universal, meaning some borrowers could be hit at both the federal and state levels. This adds another layer of complexity and potential financial strain, particularly for those in states with higher income tax rates.
The Political Quagmire: Why Was This Exemption Allowed to Expire?
This isn’t an accidental oversight; it’s a deliberate policy choice, or rather, a lack of action. The American Rescue Plan Act, passed in 2021, was a temporary measure. When it came time to consider extending the federal tax exemption for forgiven student loan debt, the Republican-led Congress chose not to preserve it. This decision, or non-decision, has significant ramifications, essentially setting the stage for the 2026 “student loan forgiveness tax bomb.”
From one perspective, some might argue that all forgiven debt should be taxed, treating it as any other form of income. The argument often centers on fiscal responsibility and preventing what some see as a handout. However, this perspective often overlooks the unique nature of student loan debt and the specific circumstances of IDR borrowers. These aren’t people who simply got a loan for free; they’ve spent decades in a system designed to help them manage unmanageable debt, often accruing more interest than they could ever pay down.
The political landscape surrounding student loan forgiveness has always been contentious. While Democratic administrations have generally pushed for broader relief and tax exemptions, Republican lawmakers have often expressed concerns about the cost to taxpayers and the moral hazard of forgiving debt. The expiration of this specific tax exemption reflects that partisan divide. Without a bipartisan consensus to extend the provision, it simply lapses, leaving borrowers in a precarious position.
What’s particularly frustrating for advocates and borrowers alike is that this isn’t a surprise. The expiration date has been known since the legislation was passed. Yet, despite the clear warning signs and the predictable impact on millions of low-income Americans, no legislative action has been taken to prevent this looming crisis. It speaks to a broader political gridlock where the immediate needs of millions of citizens can sometimes be overshadowed by ideological battles and legislative inertia. The consequence, in this case, is a potential financial disaster for those who can least afford it. (See: CDC Youth Health Profiles.)
The Broader Economic Impact and Social Media Firestorm
The potential for 3 million Americans to suddenly owe an average of nearly $12,000 in unexpected taxes isn’t just a personal problem; it has broader economic implications. When millions of households face such a significant financial shock, it can ripple through the economy. Consumer spending could decrease, savings could be depleted, and credit scores could be negatively impacted as people struggle to pay these new tax bills. For those already on the brink, this could push them over the edge into deeper financial distress, potentially leading to increased reliance on social safety nets or even bankruptcy.
Beyond the immediate economic fallout, there’s the issue of trust and public perception. Many borrowers entered IDR plans with the understanding that after a certain period, their remaining debt would be forgiven. While the tax implications were always a potential caveat, the temporary exemption offered a reprieve and set a precedent. Now, with that exemption expiring, it feels to many like the rug is being pulled out from under them. This erodes trust in government programs and can create a sense of betrayal among those who have diligently followed the rules.
It’s no wonder this issue is generating massive social media engagement and viral potential. The story is inherently shocking: relief turns into a new burden. People who have been promised a fresh start are now staring down a significant tax bill. This narrative resonates deeply, particularly in an era where financial anxiety is already high. Online discussions are filled with outrage, confusion, and calls for action. Borrowers are sharing their stories, expressing their fear and frustration, and demanding that lawmakers address this critical issue before it’s too late.
The viral nature of this story isn’t just about individual hardship; it’s about a perceived injustice. Many feel that the system is once again failing those who are trying to do the right thing. The contrast between the promise of forgiveness and the reality of a substantial tax bill is stark, making for a compelling and emotionally charged topic that is unlikely to fade from public discourse quickly. The pressure on policymakers to act will only grow as the 2025 deadline approaches and more borrowers become aware of the impending “student loan forgiveness tax bomb.”
What Can Borrowers Do Now to Prepare for the Student Loan Forgiveness Tax Bomb?
For borrowers staring down the barrel of this potential “student loan forgiveness tax bomb,” inaction isn’t an option. While legislative solutions are the ideal long-term fix, individuals need to understand their current situation and explore available strategies. First and foremost, if you are on an IDR plan and anticipate your loans being forgiven sometime after December 31, 2025, you need to start planning now.
One immediate step is to consult with a tax professional. A qualified CPA or enrolled agent can help you understand your specific tax situation, estimate potential liabilities, and explore strategies like tax planning or setting aside funds. They can also advise on whether you might qualify for insolvency exceptions, which can exempt you from taxation on forgiven debt if your liabilities exceed your assets at the time of forgiveness. However, proving insolvency can be complex and requires careful documentation, so expert guidance is crucial.
Another avenue to explore is whether you have any alternative forgiveness programs you might qualify for that are not subject to this tax bomb. For example, Public Service Loan Forgiveness (PSLF) is explicitly exempt from federal income tax. If you work for a qualifying non-profit or government employer and meet the other PSLF requirements, pursuing this path could entirely circumvent the IDR forgiveness tax issue. Similarly, discharges due to death or permanent disability are also typically tax-exempt. (See: New York Times on Student Loan Forgiveness.)
It’s also vital to ensure your contact information with your loan servicer is up to date and that you understand exactly when your loans are projected for forgiveness. The timing is everything here. If your loans are forgiven before the end of 2025, you’re in the clear federally. If it’s after, you’ll need to be prepared. Keep meticulous records of all payments and communications with your loan servicer. Knowing your exact forgiveness date will be paramount for tax planning.
Looking Ahead: The Urgent Need for Legislative Action
Ultimately, the most comprehensive solution to the “student loan forgiveness tax bomb” lies in legislative action. Advocacy groups like Protect Borrowers are sounding the alarm precisely to pressure Congress to revisit this issue and extend the federal tax exemption. Without it, millions of Americans, many of whom have diligently navigated the student loan system for decades, face a significant and unwelcome financial setback.
Lawmakers have several options if they choose to act. The simplest would be to pass legislation that permanently exempts all federal student loan forgiveness from federal income tax. This would provide clarity and certainty for all borrowers and prevent this issue from recurring. Alternatively, they could extend the existing temporary exemption for another five or ten years, buying time for a more permanent solution or allowing the economy to stabilize further.
The argument for such an extension or permanent change often centers on equity and economic stimulus. Many borrowers who benefit from IDR forgiveness are low- to middle-income individuals who would likely inject any financial relief directly back into the economy through spending, rather than saving. Furthermore, taxing forgiven debt effectively penalizes those who struggled the most, undermining the very concept of a safety net for student loan borrowers.
The clock is ticking. With the exemption expiring at the end of 2025, Congress has a limited window to act before the first wave of tax bills hits in 2026. The political will to address this issue will be a crucial test of how seriously lawmakers take the financial well-being of millions of Americans. As the social media outcry grows and more borrowers become aware of this impending crisis, the pressure on Capitol Hill will only intensify. Let’s hope that common sense and compassion prevail, preventing a devastating financial blow to those who have already endured so much on their path to student loan relief.
Trending Now
- read the full story
- our breakdown of jaw-dropping report: chatgpt for teens fails critical safety tests, posing ‘unacceptable risk’
- our breakdown of why anthropic’s shocking ban on ‘cruelty’ to claude ai will change everything
- Outrageous: Nearly 12,000 Book Bans in Schools — Here’s What Students Are Really Losing
- the complete explanation
Frequently Asked Questions
What is the student loan forgiveness tax bomb?
The student loan forgiveness tax bomb refers to the potential tax liability that borrowers may face after 2025 when forgiven student loans become taxable income. This could lead to average tax bills of around $12,000 for up to 3 million Americans, particularly affecting those with low incomes who have relied on income-driven repayment plans.
How does the student loan forgiveness tax bomb affect borrowers?
Borrowers who believe their remaining student loan balances will be forgiven may face unexpected tax bills once the temporary tax exemption expires in 2025. This situation can significantly impact their financial stability, potentially doubling or tripling their annual tax liabilities, especially for those earning under $60,000.
Why is there concern over the student loan forgiveness tax bomb?
The concern stems from the possibility that millions of borrowers, after years of diligent payments, could suddenly face hefty tax bills. Many borrowers, particularly those with modest incomes, may not be prepared for this financial burden, turning their anticipated relief into a new financial nightmare.
Who will be most affected by the student loan forgiveness tax bomb?
The most affected individuals will likely be low-income borrowers, especially those earning less than $60,000 annually. These borrowers, who have navigated income-driven repayment plans for decades, may struggle to cope with the sudden tax implications of forgiven debt.
What can borrowers do to prepare for the student loan forgiveness tax bomb?
Borrowers should start planning for the potential tax implications of forgiven loans by consulting financial advisors, exploring tax-saving strategies, and considering ways to save for the expected tax bill. Awareness and proactive financial planning can help mitigate the impact of this looming tax bomb.
What did we miss? Let us know in the comments and join the conversation.